


Your hail deductible, in one paragraph
Your hail deductible is the amount you pay out of pocket before your insurance company pays anything on a roof claim. In Texas it can be written two ways: a flat dollar figure, or a percentage of the amount your home is insured for. It applies to each claim you file, not once a year.
That single line on your declarations page decides how much of a North Texas hailstorm lands on your bank account and how much lands on the company. It is worth reading before the next storm season, not after. If you are shopping or renewing, start with the basics of home and property insurance and then go straight to the deductible section of your policy.
Flat dollar or percentage: what changes
A flat deductible is a fixed number, like $500. A percentage deductible is calculated on the insured value of your dwelling, so the dollar figure moves with your coverage amount. The Texas Department of Insurance publishes an example that makes the gap obvious.
Take a hail repair on the roof that costs $6,500. According to the Texas Department of Insurance guidance on deductibles, a policy with a $500 deductible would pay $6,000 of that repair. The same home with a 5 percent deductible, which works out to $7,500, would get nothing, because the repair costs less than the deductible.
Same storm, same roof. One homeowner gets a check for $6,000 and the other pays the whole job.
Nothing about the 5 percent policy is broken or unfair. It is a trade: the higher the deductible, the lower the cost of the policy. The problem shows up when you choose that trade without doing the math on what a mid size hail repair actually costs in your zip code.
Where to find your number
Look at the declarations page, the one or two page summary at the front of your policy. The deductible may appear more than once, because wind and hail can carry a different deductible than the one that applies to fire, theft or a burst pipe. If you see a percentage, multiply it by the Coverage A dwelling limit on that same page. That product, in dollars, is what you would pay before the company pays.
The TDI numbers behind this article
These are the figures used here, all published by the Texas Department of Insurance.
| Concept | Figure from the Texas Department of Insurance | TDI source |
|---|---|---|
| 5 percent deductible on a home insured for $150,000 | $7,500, so a $6,500 repair is not paid | What to know about deductibles |
| Flat $500 deductible on a $6,500 roof repair | The company pays $6,000 | What to know about deductibles |
| 10 year old roof with replacement cost coverage (cost $10,000, deductible $2,000) | The company pays $8,000 | Home insurance guide |
| Same roof with actual cash value (depreciated value $7,000, deductible $2,000) | The company pays $5,000 | Home insurance guide |
| Wind and hail on the Texas coast | May not be covered by the home policy | Home insurance guide |
Why the deductible applies to each claim
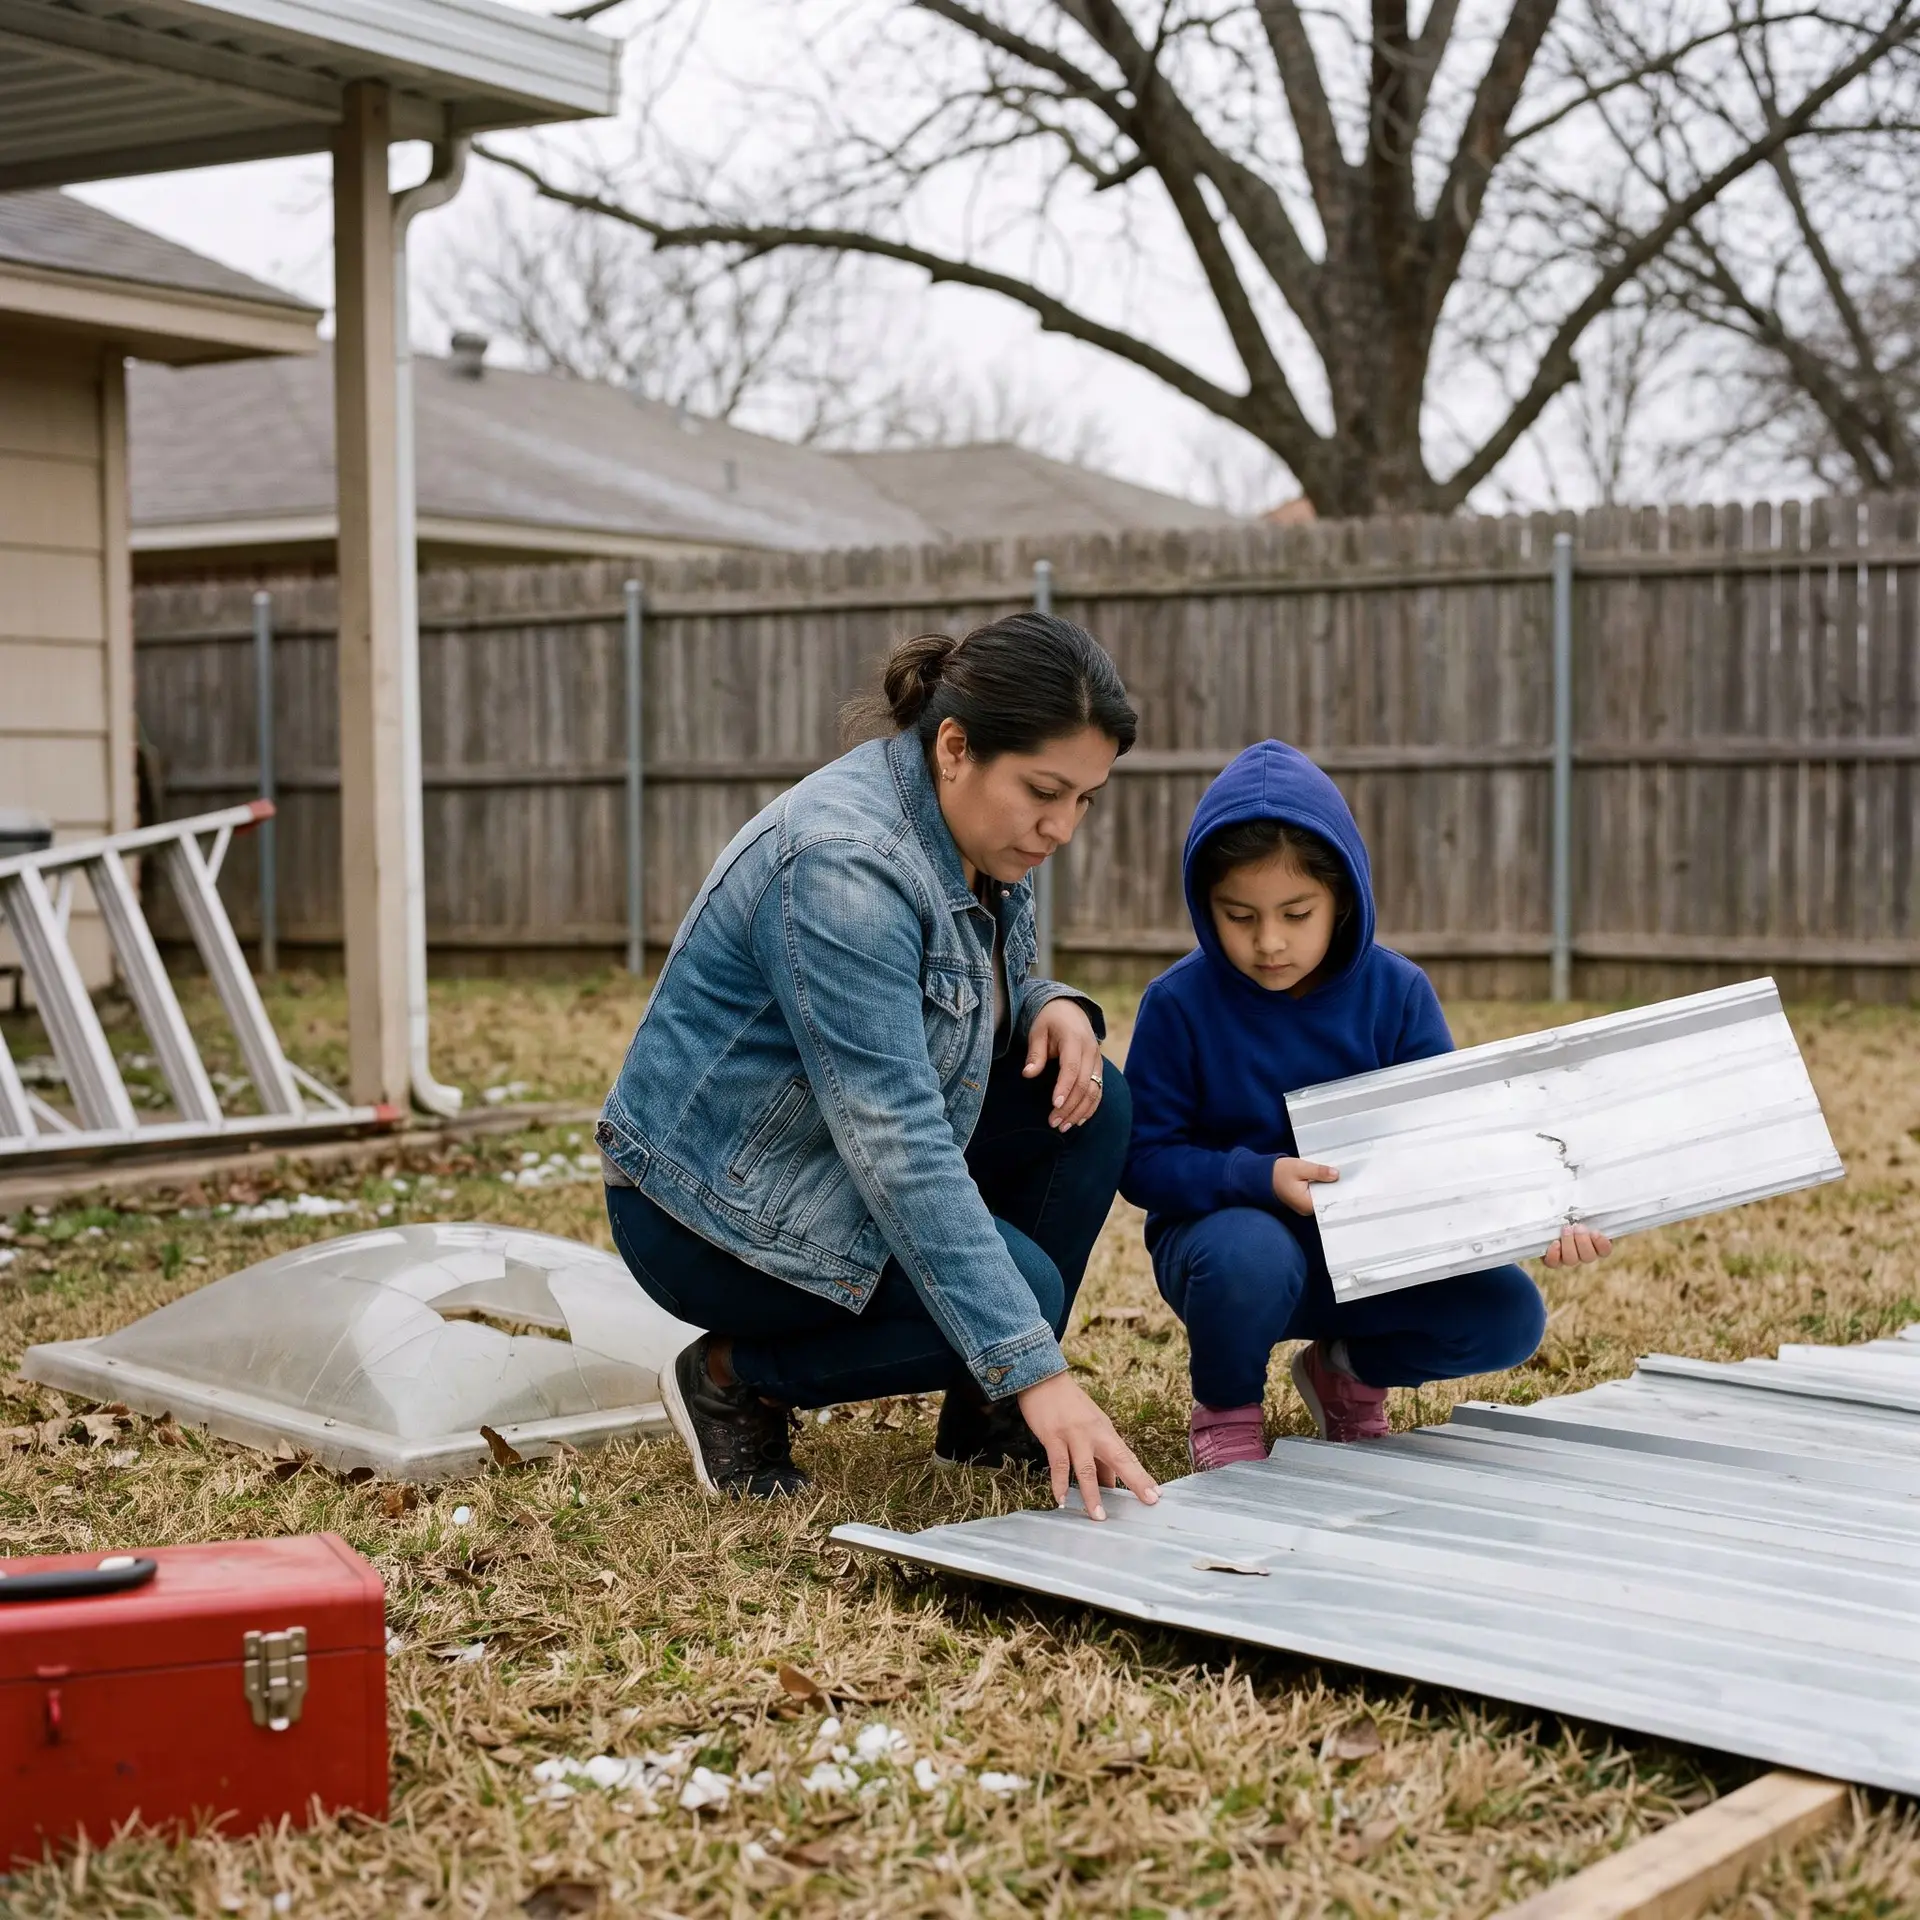
On a home policy the deductible applies to each claim, not once per calendar year, as the Texas Department of Insurance explains in its deductibles guidance. Two separate hail events in the same spring mean two separate claims and two separate deductibles. It does not reset in January and it does not carry over from one storm to the next.
That matters in North Texas because the roof is the part of the house most exposed. Carrollton, Plano, Haltom City and Ennis all sit well inland. For inland homes, the Texas Department of Insurance notes in its home insurance guide that most policies cover windstorm, hurricane and hail. The exception is homes on the Gulf coast, where wind and hail coverage may have to be bought separately.
North Texas is not the coast. Your hail exposure is real, but the coverage structure is different from a house in Harris County on Galveston Bay.
Replacement cost or actual cash value on the roof
Replacement cost pays what it costs to replace the damaged property today. Actual cash value pays replacement cost minus depreciation, which means the older the roof, the less you collect. This one word in your policy can move a hail check by thousands of dollars.
The Texas Department of Insurance uses a 10 year old roof to show it. If replacing it costs $10,000 and your deductible is $2,000, a replacement cost policy pays $8,000. Under actual cash value, the depreciated value of that roof is set at $7,000, so after the same $2,000 deductible the company pays $5,000.
Three thousand dollars of difference, from one line in the contract.
Two questions to ask your agent
- Is my roof covered at replacement cost or at actual cash value, and does that change as the roof ages?
- Is my wind and hail deductible the same as my all other perils deductible, or is it a separate percentage?
Write the answers down. When hail hits, you want to already know what you are working with instead of reading forty pages on a Tuesday night with a tarp on the roof.
What to do in the days after a hailstorm
Tell your insurance company as soon as possible, because most companies set deadlines for reporting damage. Make only temporary repairs to stop further damage. Permanent repairs done before the company has seen the damage can lead to a denied claim.
Temporary versus permanent
Temporary is a tarp over an opening, boarding a broken window, moving furniture away from a leak, shutting off water to a damaged line. Permanent is a new roof, new decking, new drywall. Keep receipts for the temporary work and take photos before and after. Include wide shots that show the whole elevation of the house and close shots of the impact marks.
The clock on your claim
Once the company has all the information it needs from you, it must accept or deny your claim within 15 business days. If it agrees to pay, it must pay within five business days after that. Those deadlines run from the moment your file is complete. That is one more reason to send documents quickly and in one organized batch instead of one photo at a time.
If the same storm also dented the cars in the driveway, that is a separate policy and a separate deductible. We walk through that process in our guide to Texas car insurance after a hail storm and in our explainer on extreme weather and Texas car insurance.
Choosing your deductible before renewal
Before your renewal, check whether your deductible is a flat amount or a percentage, and convert the percentage into dollars so the number stops being abstract. Then ask yourself a plain question: if a hail repair came in under that figure, could you absorb it without touching savings you need for something else?
A higher deductible lowers what you pay for the policy. A lower deductible raises it. Neither answer is right for everybody, and the honest version of this conversation includes the possibility that your current setup is already fine. What is not fine is finding out the number for the first time while an adjuster is on your roof.
Univista Insurance has North Texas offices in Carrollton, Plano, Haltom City and Ennis. Our licensed agents compare more than 20 companies in a free quote, by phone, online or in person, in English or Spanish. Bring your declarations page. Fifteen minutes with it open answers most of what this article raises.
Frequently asked questions
More answers about coverage, claims and limits are collected in our homeowners insurance FAQ.
How is a percentage hail deductible calculated in Texas?
It is applied to the amount your home is insured for, not to the cost of the repair. The Texas Department of Insurance gives the example of a 5 percent deductible on a home insured for $150,000, which equals $7,500. A $6,500 roof repair would receive no payment at all.
Is the hail deductible the same as my general policy deductible?
Not necessarily. Many policies carry a separate deductible for wind and hail damage, different from the one applied to other types of loss. It may be written as a percentage while the other is a flat dollar amount. Check both figures on your declarations page.
How many times do I pay the deductible if two hailstorms hit in one year?
Once for each claim. The Texas Department of Insurance states that on home policies the deductible applies to each claim, not once per calendar year. Two storms, two claims, two deductibles, even if they happen weeks apart and damage the same roof.
Review your hail deductible with an agent and get a quote before the next storm season.
 Vehicle
 Home & Property
 Commercial
 Life
 Health